
Thinkmoney Credit Builder Card: rebuild your credit with simple and manageable payments
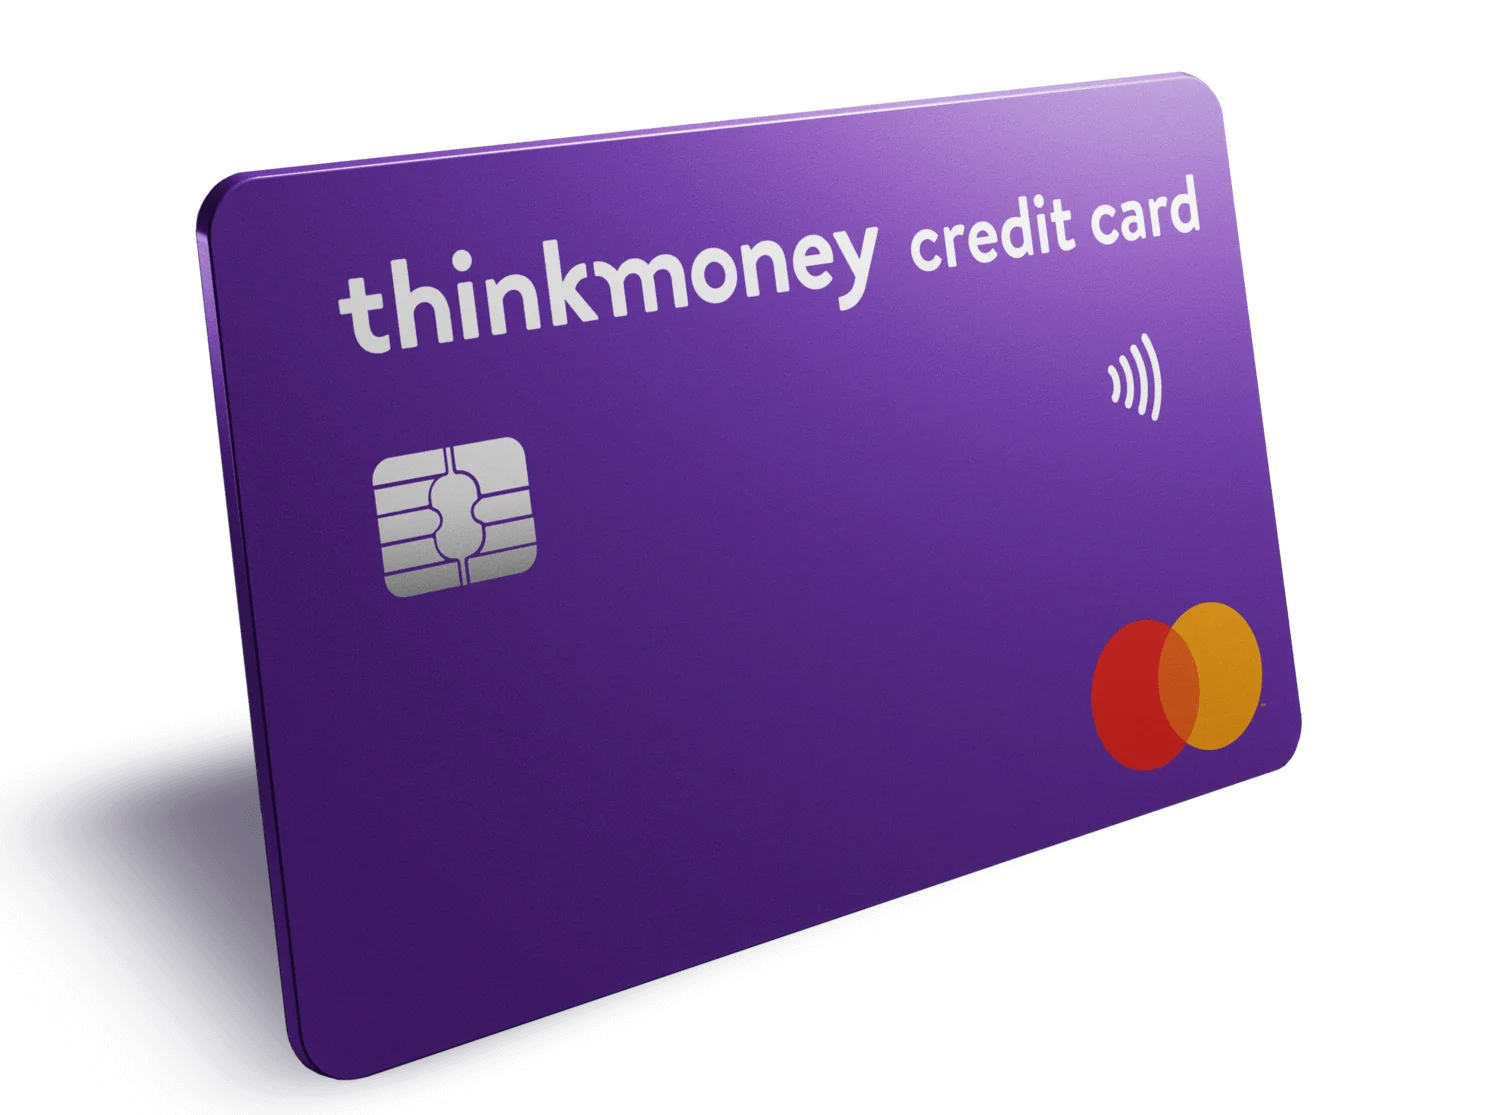
The thinkmoney Credit Builder Card is a digital‑first Mastercard product promoted by thinkmoney and issued in partnership with Capital One (Europe) plc. It is presented as a credit‑building option for UK residents who want to establish or rebuild a credit history while managing their account through the card lender’s account services.
The product emphasises simple, app-driven account management and a QuickCheck pre‑qualification feature that, according to the issuer, can be used without impacting your credit score.The publicly disclosed maximum borrowing level for the product is up to £4,000. Eligibility rules published by the issuer state that applicants must be at least 18 years old and must live in the UK for at least six months each year.
The current thinkmoney product page advertises 39.9% representative APR (variable). Eligible customers may qualify for 0% on purchases and balance transfers for 6 months; a 2.9% transfer fee applies. Your offered rate, limit and promotion depend on assessment.
Benefits
The thinkmoney Credit Builder Card is designed to offer predictable, digitally managed credit access for people focusing on rebuilding or establishing credit. Primary benefits emphasised in the public material include:
- Soft eligibility check: a QuickCheck/pre‑qualification option is available and described as not impacting your credit score.
- Credit‑building focus: intended to help demonstrate regular repayments and improve a credit record over time when used responsibly.
- Mobile app management: account administration and monitoring are designed to be handled through the Capital One card account services.
- Manageable credit limits: the publicly stated maximum credit limit for the product is £4,000, which positions it as an entry‑level credit facility rather than a premium rewards card.
Prerequisites
According to the issuer’s published eligibility notes, the following requirements apply:
- Minimum age: 18 years.
- Residency: you must be a resident of the UK and live in the UK for at least six months of every year.
- Pre‑qualification: thinkmoney advertises a QuickCheck soft search option described as “Check without impacting your score” for an initial eligibility view.
Income requirements, minimum income thresholds and explicit credit‑score cutoffs are not disclosed by the issuer as of 2025-09-16.
Who is this card for?
This card is primarily aimed at people who need to establish or rebuild a UK credit history and who prefer a straightforward, app‑driven banking experience. It is most suitable for applicants who:
- have a limited or impaired credit history and want a product specifically marketed for credit building;
- prefer to manage accounts via a smartphone app and online portal rather than visiting branches;
- want to use a modest, manageable credit line to demonstrate on‑time repayments over time.
The product is not positioned as a premium rewards or travel card; it is framed as an entry‑level credit option with predictable servicing and a focus on rebuilding creditworthiness rather than offering extensive loyalty or travel perks.
What rewards and programs does the card offer?
This thinkmoney card focuses on managing borrowing and building a payment history. The current product page does not advertise a points or cashback programme. Its potential benefit is a conditional introductory interest offer, not a cash reward. A transfer fee still adds to your balance, and missed payments can damage your credit record.
Decide whether a promotion helps by comparing the debt you can afford to repay during the offer with the total transferred balance and fee. Keep making payments on the old card until a transfer is confirmed. Do not assume a transfer will close the old account or cancel its Direct Debit.
Initial credit limit
The issuer’s public information confirms a maximum credit limit for the product but does not publish a guaranteed initial limit for new customers. Key points:
- Maximum credit limit: up to £4,000 (publicly stated).
- Minimum credit limit: Not disclosed by issuer as of 2025-09-16.
When specific initial or minimum credit limits are not published, banks commonly decide a starting credit limit based on factors such as the applicant’s credit history, income and affordability checks, the result of any pre‑qualification or soft search, and internal risk models. For credit‑builder cards in particular, issuers may set modest starting limits and allow increases over time following evidence of responsible account use.
Step by step to apply for the card
Below is a practical sequence to request the thinkmoney Credit Builder Card based on the issuer’s online application flow and publicly disclosed procedures:
- Read the official product page and the linked terms and conditions to understand eligibility and product design. The thinkmoney product page is the primary source of product information.
- Use the QuickCheck/pre‑qualification tool advertised on the product page to check likely eligibility without a hard credit search. The issuer describes this as a soft check that will not affect your credit score.
- If the QuickCheck indicates you are likely eligible, proceed to the full online application via the issuer’s apply URL. Complete all sections, including personal details, residency, income (if requested) and identification information.
- Submit the application and await the issuer’s decision. The issuer may perform standard identity and affordability checks as part of the full application process.
- If approved, you will receive account opening details and instructions for activating and managing the card in the card lender’s account service or online portal.
To start an application, use the official online application link here:
TAP TO ACCESS THE CARD WEBSITE
You can also review the product and supporting documents on the issuer’s product page: thinkmoney Credit Builder Card product page.
Card’s pros and cons
Below is a balanced view of this Capital One-issued product promoted by thinkmoney. Compare the personalised offer carefully before accepting.
Pros
- Soft QuickCheck pre‑qualification that the issuer states will not impact your credit score.
- Designed to help establish or rebuild credit when used with consistent, on‑time payments.
- Mobile‑first management via the card lender’s account service offers convenience for customers who prefer digital account servicing.
- Clear maximum credit limit published (£4,000), indicating the product is intended as an entry‑level credit facility rather than a high‑limit premium card.
Cons
- The 39.9% representative APR (variable) makes long-term borrowing expensive. Your actual rate and promotional eligibility are confirmed before you accept the agreement.
- Review the personalised quotation and Capital One agreement before applying; a representative rate does not guarantee the same rate for every applicant.
- There is no rewards programme disclosed for the product; if you prioritise rewards or cashback, this card may not meet that need.
- Compare the offer shown on thinkmoney’s current page with the exact agreement you receive, because other Capital One cards can have different representative examples.
How to unlock the card?
Follow the activation instructions issued by Capital One with your new card. Use the lender’s official account service or the telephone number printed on the card to confirm activation and access. thinkmoney’s current-account banking app is not evidence that it services this credit card.
If your accepted offer includes a balance transfer, follow the transfer process described in the Capital One agreement. Confirm the destination card details, fee and transfer deadline before submitting a request. Continue paying your old lender until both accounts show that the transfer has completed. Report any unexpected delay through the card lender’s verified support channel.
Fees and tariffs
thinkmoney advertises 39.9% representative APR (variable), with personalised rates from 28.9% APR (variable). Qualifying customers may receive 0% on purchases and balance transfers for 6 months, with a 2.9% balance-transfer fee. Review the exact offer before accepting: the headline promotion is conditional, and standard interest applies when it ends.
Capital One supplies the credit; thinkmoney acts as a broker. Read the Capital One credit agreement for annual fees, late-payment charges, foreign usage, cash withdrawals and transfer limits for your offer. Do not apply a different card’s fees or limits to this product. A transfer fee is added to your debt, so include it when calculating how much you need to repay each month.
Customer service
The issuer publishes the following official contact channels and pages that applicants can use for help or to confirm product details:
- Official product page: thinkmoney Credit Builder Card product page.
- Apply online: use the issuer application page
- Terms and conditions (partner issuer): thinkmoney product terms on Capital One site.
- Credit-card support: Use the number on the back of the card or the official Capital One contact route specified in your welcome pack.
- App store pages: iOS app and Android app.
- PDF terms (issuer T&Cs): thinkmoney terms and conditions (PDF).
The links below are for thinkmoney banking apps. They serve the banking account and should not be treated as credit-card activation or servicing instructions; follow Capital One’s card welcome pack for the correct service.
No dedicated email address or chat URL was clearly published in the materials reviewed; contact hours were also not published in a concise form in the issuer pages reviewed.
Important disclaimers and next steps
This article is for educational purposes and is not personalised financial advice. Product terms, eligibility and pricing can change; where the issuer has not published a price or a fee, this article states that fact as of 2025-09-16. Before applying, you should read the issuer’s full terms and conditions, confirm current rates and fees, and consider how the product fits your financial situation. Always aim to repay revolving balances in full where possible to avoid interest charges and to build a positive repayment history.
About the author

A journalist and advertiser by training, I'm passionate about music, TV shows, books, and everything related to pop culture. I love learning new languages and exploring the traditions and customs of different countries. What I enjoy most about working in communication is writing and creating SEO-focused content that makes information practical, accessible, and useful for anyone looking to learn or stay informed.


